Notification
Go to Home All Tools Compare Glossary Blog Contact

Loan Calculator

Calculate your loan EMI, total interest, and full repayment schedule for home, car, or personal loans in seconds.

✓ Embeddable
Currency
₹
₹10,000 ₹1 Crore ₹2 Crores+
%
1% 13% 25%
Slide or Type Value
Years
1 Year 30 Years
Repayment Summary
Monthly Loan EMI

₹0

Total Interest Payable ₹0
Total Repayment Amount ₹0
Breakdown Split
Principal
Interest Component
Personal Finance Guide

Loan Calculator – Debt & Amortization Guide

A Loan Calculator computes total monthly installment costs, interest burdens, and amortization schedules for personal, auto, student, or business loans.

What is a Loan Calculator?

An online tool that models exact monthly loan repayment obligations, principal reduction curves, and total interest charges across variable interest rates and terms.

Key Benefits of Using a Loan Calculator

  • Accurate Cost Visibility: Know exact monthly obligations before signing loan contracts.
  • Interest Minimization: Adjust loan terms to find the sweet spot between low monthly payments and lower total interest.
  • Lender Comparison: Compare competitive loan quotes from different banks side by side.

How Loan Amortization Works (Live Example)

Calculated for a principal loan of $25,000 at 7.00% annual interest rate over a 5-year (60 months) tenure:

Loan Principal $25,000
Interest Rate 7.00% p.a.
Loan Term 5 Years
Payment Cycle Monthly
• Monthly Installment Payment: $495.03 / month
• Total Cumulative Interest Paid: ($495.03 × 60) − $25,000 = $4,701.76
• Total Paid Over 5 Years: Principal $25,000 + Interest $4,701.76 = $29,701.76
Principal: $25,000 Interest Cost: $4,701.76 Monthly Payment: $495.03
1

Enter Principal

Input total requested loan amount.

2

Set Rate & Term

Select interest rate % and loan tenure in years or months.

3

View Amortization

Review monthly payments, breakdown split, and full amortization table.

Amortisation Ledger

Yearly Payoff Schedule

Repayment breakdown of linear interest depletion components

Year Principal Paid Interest Paid Ending Balance
Year 1 ₹49,756 ₹210,591 ₹2,450,244
Year 2 ₹54,154 ₹206,193 ₹2,396,091
Year 3 ₹58,940 ₹201,407 ₹2,337,150
Year 4 ₹64,150 ₹196,197 ₹2,273,000
Year 5 ₹69,820 ₹190,527 ₹2,203,180
Year 6 ₹75,992 ₹184,355 ₹2,127,188
Year 7 ₹82,709 ₹177,638 ₹2,044,479
Year 8 ₹90,020 ₹170,327 ₹1,954,459
Year 9 ₹97,977 ₹162,370 ₹1,856,482
Year 10 ₹106,637 ₹153,710 ₹1,749,846
Year 11 ₹116,063 ₹144,284 ₹1,633,783
Year 12 ₹126,321 ₹134,026 ₹1,507,462
Year 13 ₹137,487 ₹122,860 ₹1,369,974
Year 14 ₹149,640 ₹110,707 ₹1,220,335
Year 15 ₹162,866 ₹97,480 ₹1,057,468
Year 16 ₹177,262 ₹83,085 ₹880,206
Year 17 ₹192,931 ₹67,416 ₹687,275
Year 18 ₹209,984 ₹50,363 ₹477,291
Year 19 ₹228,545 ₹31,802 ₹248,746
Year 20 ₹248,746 ₹11,601 ₹0
Debt Optimisation Companion

AI Advisor Debt Strategist

Ask AI
Education

Understanding Loan Repayments

01

Principal and Interest Explained

Every loan payment consists of principal and interest. The principal is the amount borrowed, while interest is the lender's charge for providing the loan. Understanding this breakdown helps borrowers evaluate the true cost of financing.
02

Loan Term Affects Total Cost

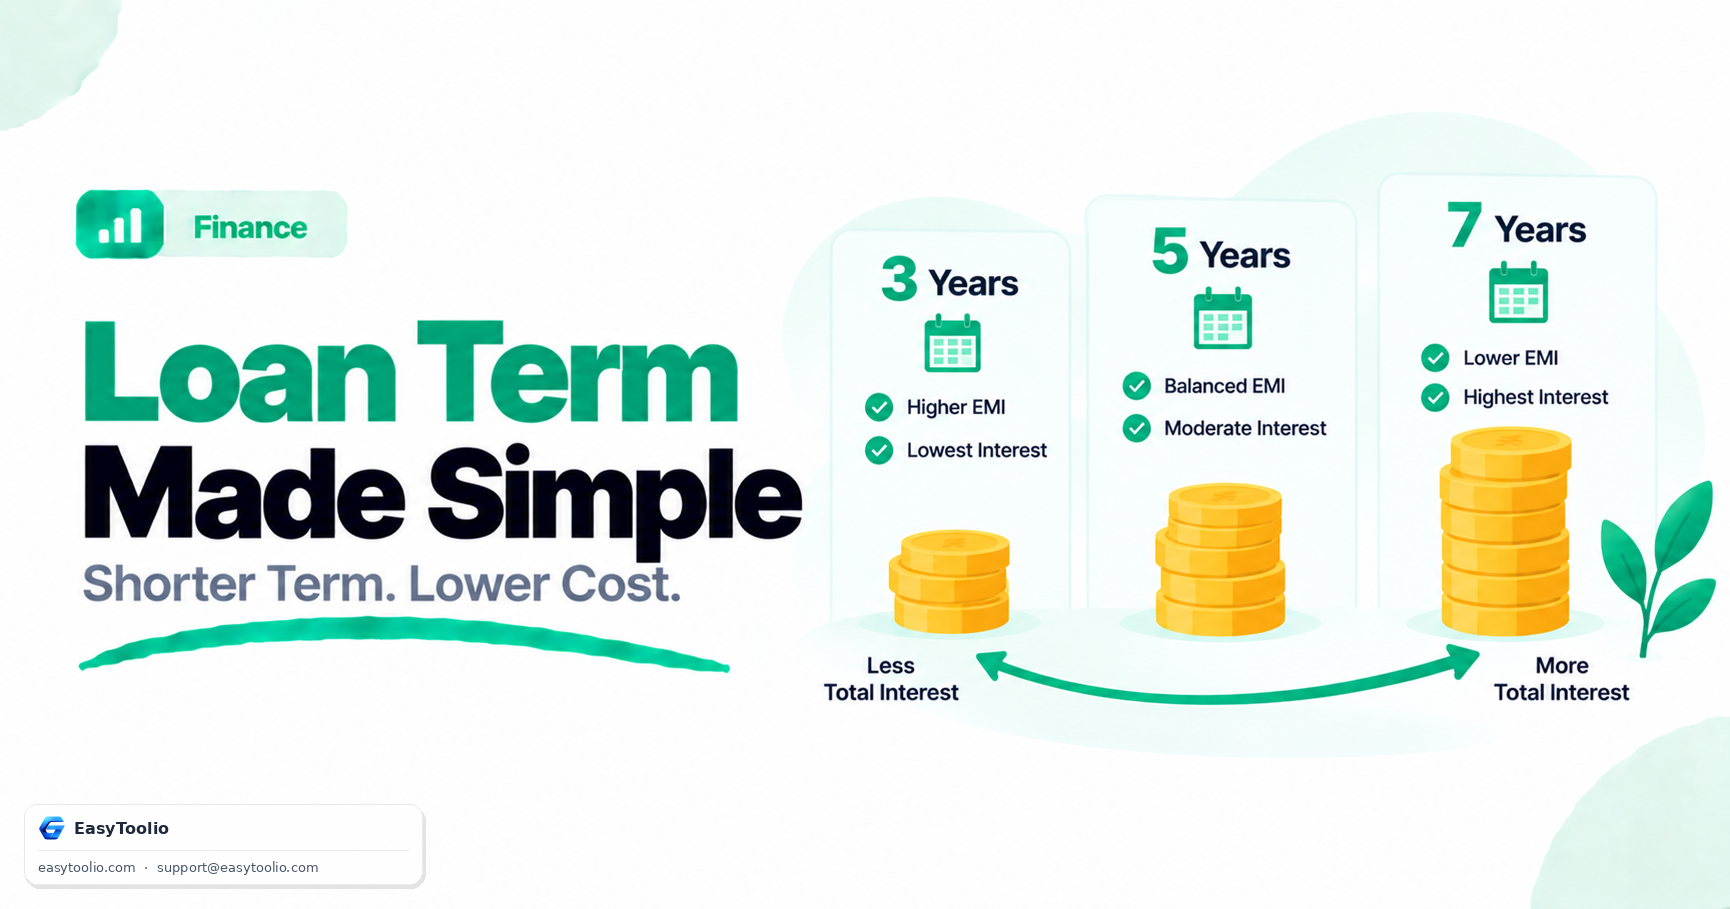
Choosing a longer loan term can reduce monthly payments, but it usually increases the total interest paid over time. Shorter loan terms often save money overall, though they require higher monthly installments.

03

Interest Rates Matter More Than You Think

Even a small difference in interest rates can significantly impact your monthly payment and total repayment amount. Comparing loan offers from multiple lenders can help reduce borrowing costs substantially.

04

Early Payments Can Save Money

Making additional payments toward your loan balance can shorten the repayment period and lower total interest costs. Consistent extra payments often result in meaningful savings over the life of the loan.

Good to know

Questions, answered

Quick answers about how this tool works.

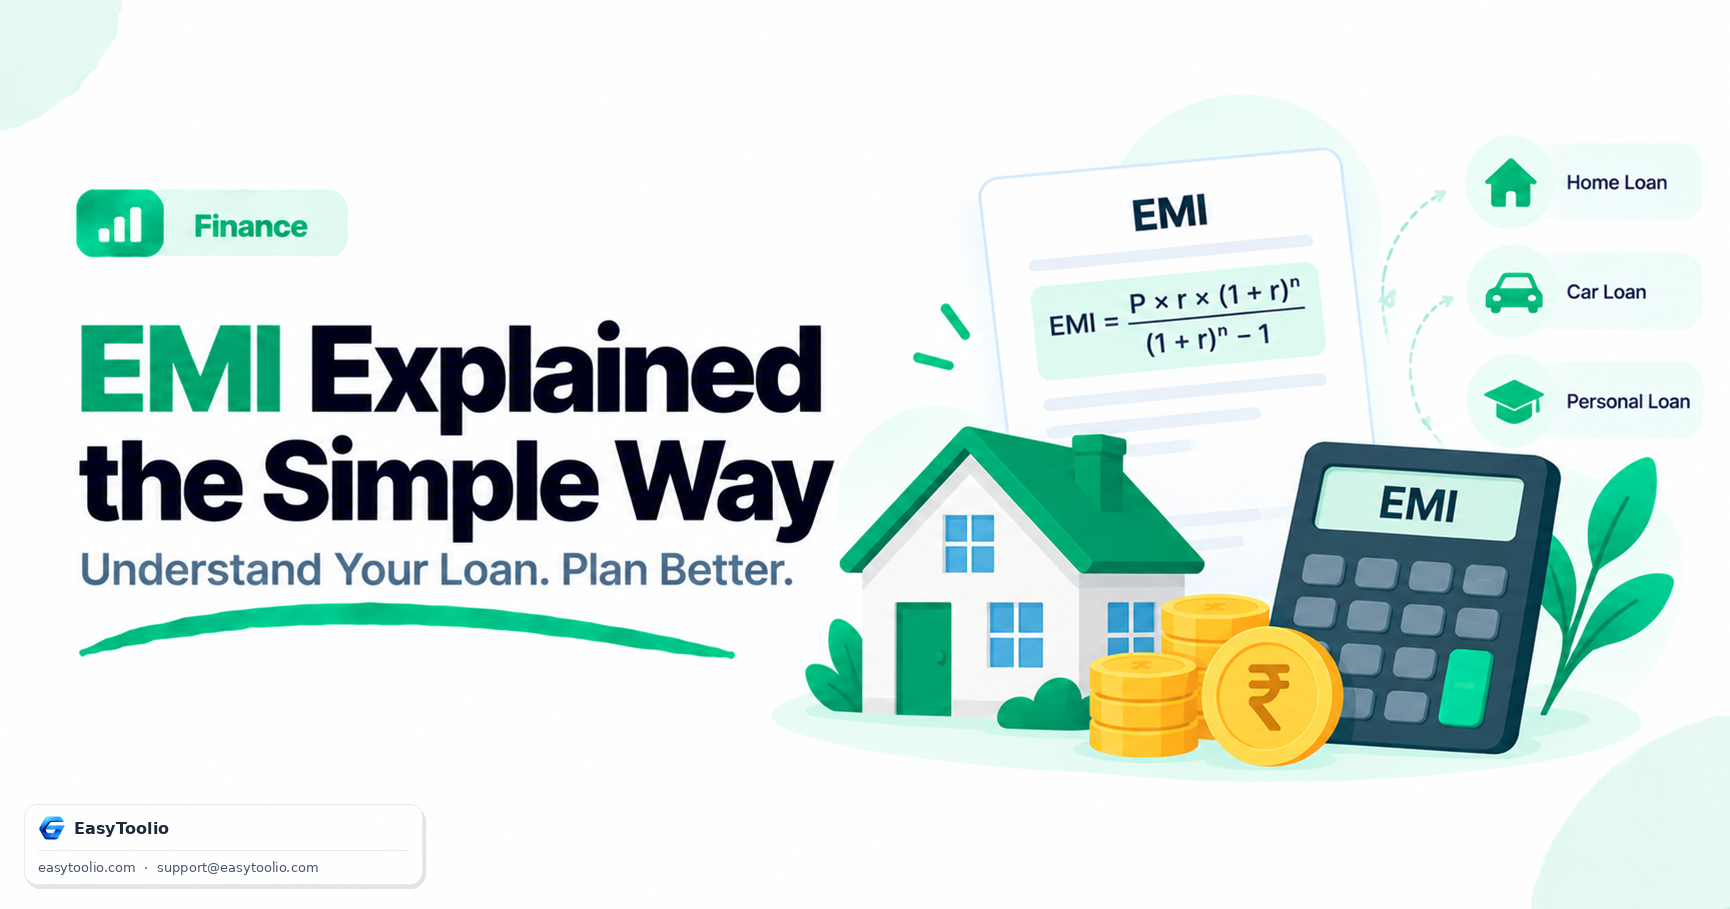
Under a Reducing Balance method, interest is calculated only on the outstanding principal balance remaining after each payment. In a Flat Rate Loan, interest is calculated on the entire original loan amount throughout the loan tenure, resulting in a higher overall borrowing cost.

According to RBI guidelines, individual borrowers with floating-rate home loans are generally not charged foreclosure or prepayment penalties. However, lenders may still impose charges on certain fixed-rate loans or commercial borrowing products.

Increasing your monthly EMI helps reduce the outstanding principal faster. Since interest is calculated on the remaining loan balance, a lower principal results in reduced interest costs and can significantly shorten the overall loan tenure.

A loan calculator helps estimate monthly loan payments, total interest costs, and total repayment amounts based on the loan amount, interest rate, and repayment tenure. It allows borrowers to compare different loan scenarios before applying.

Guides

Related guides

Plain-language explainers that sit next to this tool.

Embed Loan Calculator

Free

What do you need to work out next?

Search 244+ free tools by name, or pick a category below. Every one runs instantly in your browser — no signup, nothing to install.

More Finance tools