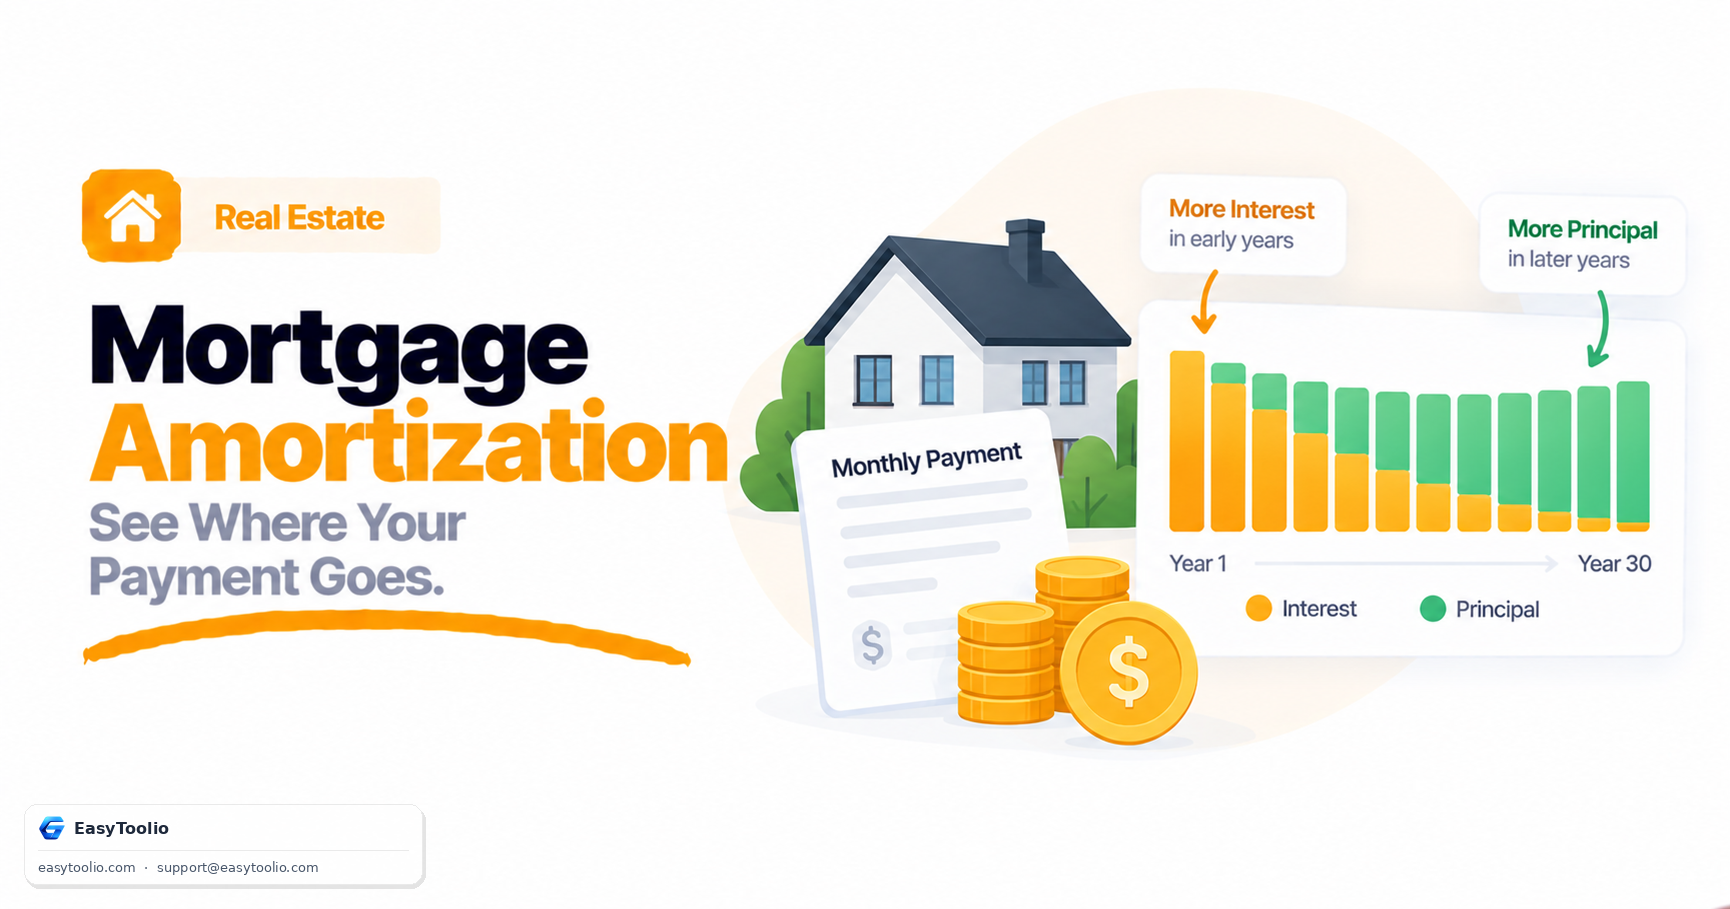
Look at your first year of mortgage statements and you might notice something unsettling: after twelve months of payments, your outstanding loan balance has barely moved. This isn't a mistake or a hidden fee — it's how amortization works, and understanding the mechanics behind it changes how you think about extra payments, refinancing, and loan tenure.
Direct Answer: Every fixed monthly mortgage payment is split into two parts: principal (which reduces your actual loan balance) and interest (the cost of borrowing, calculated on your remaining balance). Because interest is charged on whatever balance is still outstanding, and that balance is at its highest at the very start of the loan, the interest portion of your payment is largest in the early years and steadily shrinks as the principal portion grows — even though your total monthly payment stays the same.
1. How Each Payment Splits: The Core Mechanism
At the start of any month, the interest due is calculated as:
Monthly Interest = Remaining Loan Balance × Annual Interest Rate ÷ 12
Whatever is left over from your fixed monthly payment after that interest is deducted goes toward reducing the principal:
Principal Portion = Fixed Monthly Payment - Monthly Interest
Because the remaining balance decreases with every payment, the interest amount decreases too — which means the principal amount must increase to keep the total payment fixed. This is the entire mechanism behind an amortization schedule.
2. Why the Split Looks So Different Early vs Late in the Loan
Consider a simplified example: a loan of $300,000 at a 7% annual interest rate, with a fixed monthly payment of approximately $1,996 (a common result for a 30-year term at that rate).
First payment (Month 1):
Interest = 300,000 × 0.07 ÷ 12 = 1,750
Principal = 1,996 - 1,750 = 246
Here, interest consumes about 88% of the payment, and only 12% actually reduces the loan balance.
A mid-term payment (roughly Year 15, remaining balance around $220,000):
Interest = 220,000 × 0.07 ÷ 12 ≈ 1,283
Principal = 1,996 - 1,283 = 713
By this point, principal makes up about 36% of the payment — a dramatically larger share than in month one, purely because the outstanding balance the interest is calculated on has shrunk.
| Payment Stage | Approx. Remaining Balance | Interest Portion | Principal Portion |
|---|---|---|---|
| Month 1 | $300,000 | ~$1,750 (88%) | ~$246 (12%) |
| Year 15 (mid-term) | ~$220,000 | ~$1,283 (64%) | ~$713 (36%) |
This is why a mortgage's early years feel like "mostly paying interest" — because, mechanically, that's exactly what's happening.
3. Why Extra Payments Made Early Save More Total Interest
Since interest is always calculated on the current remaining balance, any extra payment that reduces principal early in the loan reduces the balance that every subsequent month's interest is calculated against — compounding the savings over the rest of the term.
An extra principal payment made in month 1 reduces the balance for all 359 remaining months of interest calculations on a 30-year loan. The same extra payment made in month 300 (25 years in) only affects interest calculations for the remaining 60 months.
Total Interest Saved ∝ Extra Principal Paid × Remaining Months It Reduces Interest On
This is why financial guidance consistently emphasizes making extra principal payments as early as possible in a mortgage: the same dollar amount saves meaningfully more in total interest paid over the life of the loan the earlier it's applied, because it removes that principal from the balance for a longer stretch of remaining compounding periods.
4. What This Means Practically for Borrowers
- A 30-year loan front-loads interest, not by design malice, but by mathematical necessity — the balance is highest at the start, so interest (a percentage of that balance) is also highest at the start.
- Refinancing resets the clock. Refinancing into a new loan restarts amortization from the beginning, meaning you'll pass through another high-interest, low-principal early phase — worth weighing carefully if you're already many years into your current term.
- Bi-weekly or extra annual payments accelerate principal reduction disproportionately when made early, because of the compounding effect described above.
- Your remaining balance, not your original loan amount, always determines next month's interest — this is the single fact that explains the entire shape of an amortization schedule.
Generate your own full amortization schedule with our mortgage-calculator, compare loan structures using the loan-calculator, and weigh long-term ownership costs against renting with the rent-vs-buy-calculator.
5. Frequently Asked Questions (FAQs)
Does making one extra payment a year actually make a meaningful difference?
Yes, particularly if made early in the loan term. Because that extra amount reduces principal — and therefore the balance all future interest is calculated on — even a single well-timed extra payment early in a 30-year mortgage can meaningfully shorten the loan term and reduce total interest paid, more than the same payment would achieve if made in the loan's final years.
Why does my loan balance barely decrease after a year of payments on a 30-year mortgage?
In the early years, the vast majority of each payment is consumed by interest on the (still very high) remaining balance, leaving only a small fraction to actually reduce principal. This is a direct mathematical consequence of how interest is calculated on the outstanding balance, not an error in your statement.
If I refinance to a lower interest rate, will my payment split change immediately?
Yes. Refinancing replaces your existing loan with a new one, and the new loan's amortization schedule starts fresh from its own new principal balance and new rate — meaning the interest-heavy early phase repeats, though typically at a lower interest rate than before if the refinance was rate-motivated.
References: Standard fixed-rate mortgage amortization methodology, as used in conventional loan amortization schedule calculations.